Close Menu
Your Life After RetirementYour Life After Retirement
  • Home
  • Retirement News
  • Lifestyle
  • Fitness
  • Wellness
  • Senior Health
  • Finance
  • Medicare & Insurance
Top Post

Not glamorous, but common: how to manage dandruff at home and when to get help | Well actually

September 13, 2026

7-Day Menu and Comprehensive Food List

September 13, 2026

Paul George Is Hoping His New Approach to Training Will Lead to an Injury-Free Season

September 13, 2026
Facebook X (Twitter) Instagram
Trending
  • Not glamorous, but common: how to manage dandruff at home and when to get help | Well actually
  • 7-Day Menu and Comprehensive Food List
  • Paul George Is Hoping His New Approach to Training Will Lead to an Injury-Free Season
  • I Tried Rag & Bone’s Viral Sweatpants Jeans—Here’s Why I Love Them for Travel
  • Why the 4% Rule Could Fail for Retirement Income
  • King Charles Could Recreate One of Queen Elizabeth’s Eton Rituals
  • AI could make humans extinct say researchers
  • LIMRA: Final Q2 Annuity Sales Lower Than Expected
Monday, September 14
Your Life After Retirement
  • Home
  • Retirement News
  • Lifestyle
  • Fitness
  • Wellness
  • Senior Health
  • Finance
  • Medicare & Insurance
Your Life After Retirement
Home»Finance»3 Questions to Ask Before You Roll Over an Old 401(k)
Finance

3 Questions to Ask Before You Roll Over an Old 401(k)

yourlifeafterretirementBy yourlifeafterretirementJune 14, 2026
3 Questions to Ask Before You Roll Over an Old 401(k)
Share
Facebook Twitter LinkedIn

We research all brands listed and may earn a fee from our partners. Research and financial considerations may influence how brands are displayed. Not all brands are included. Learn more.

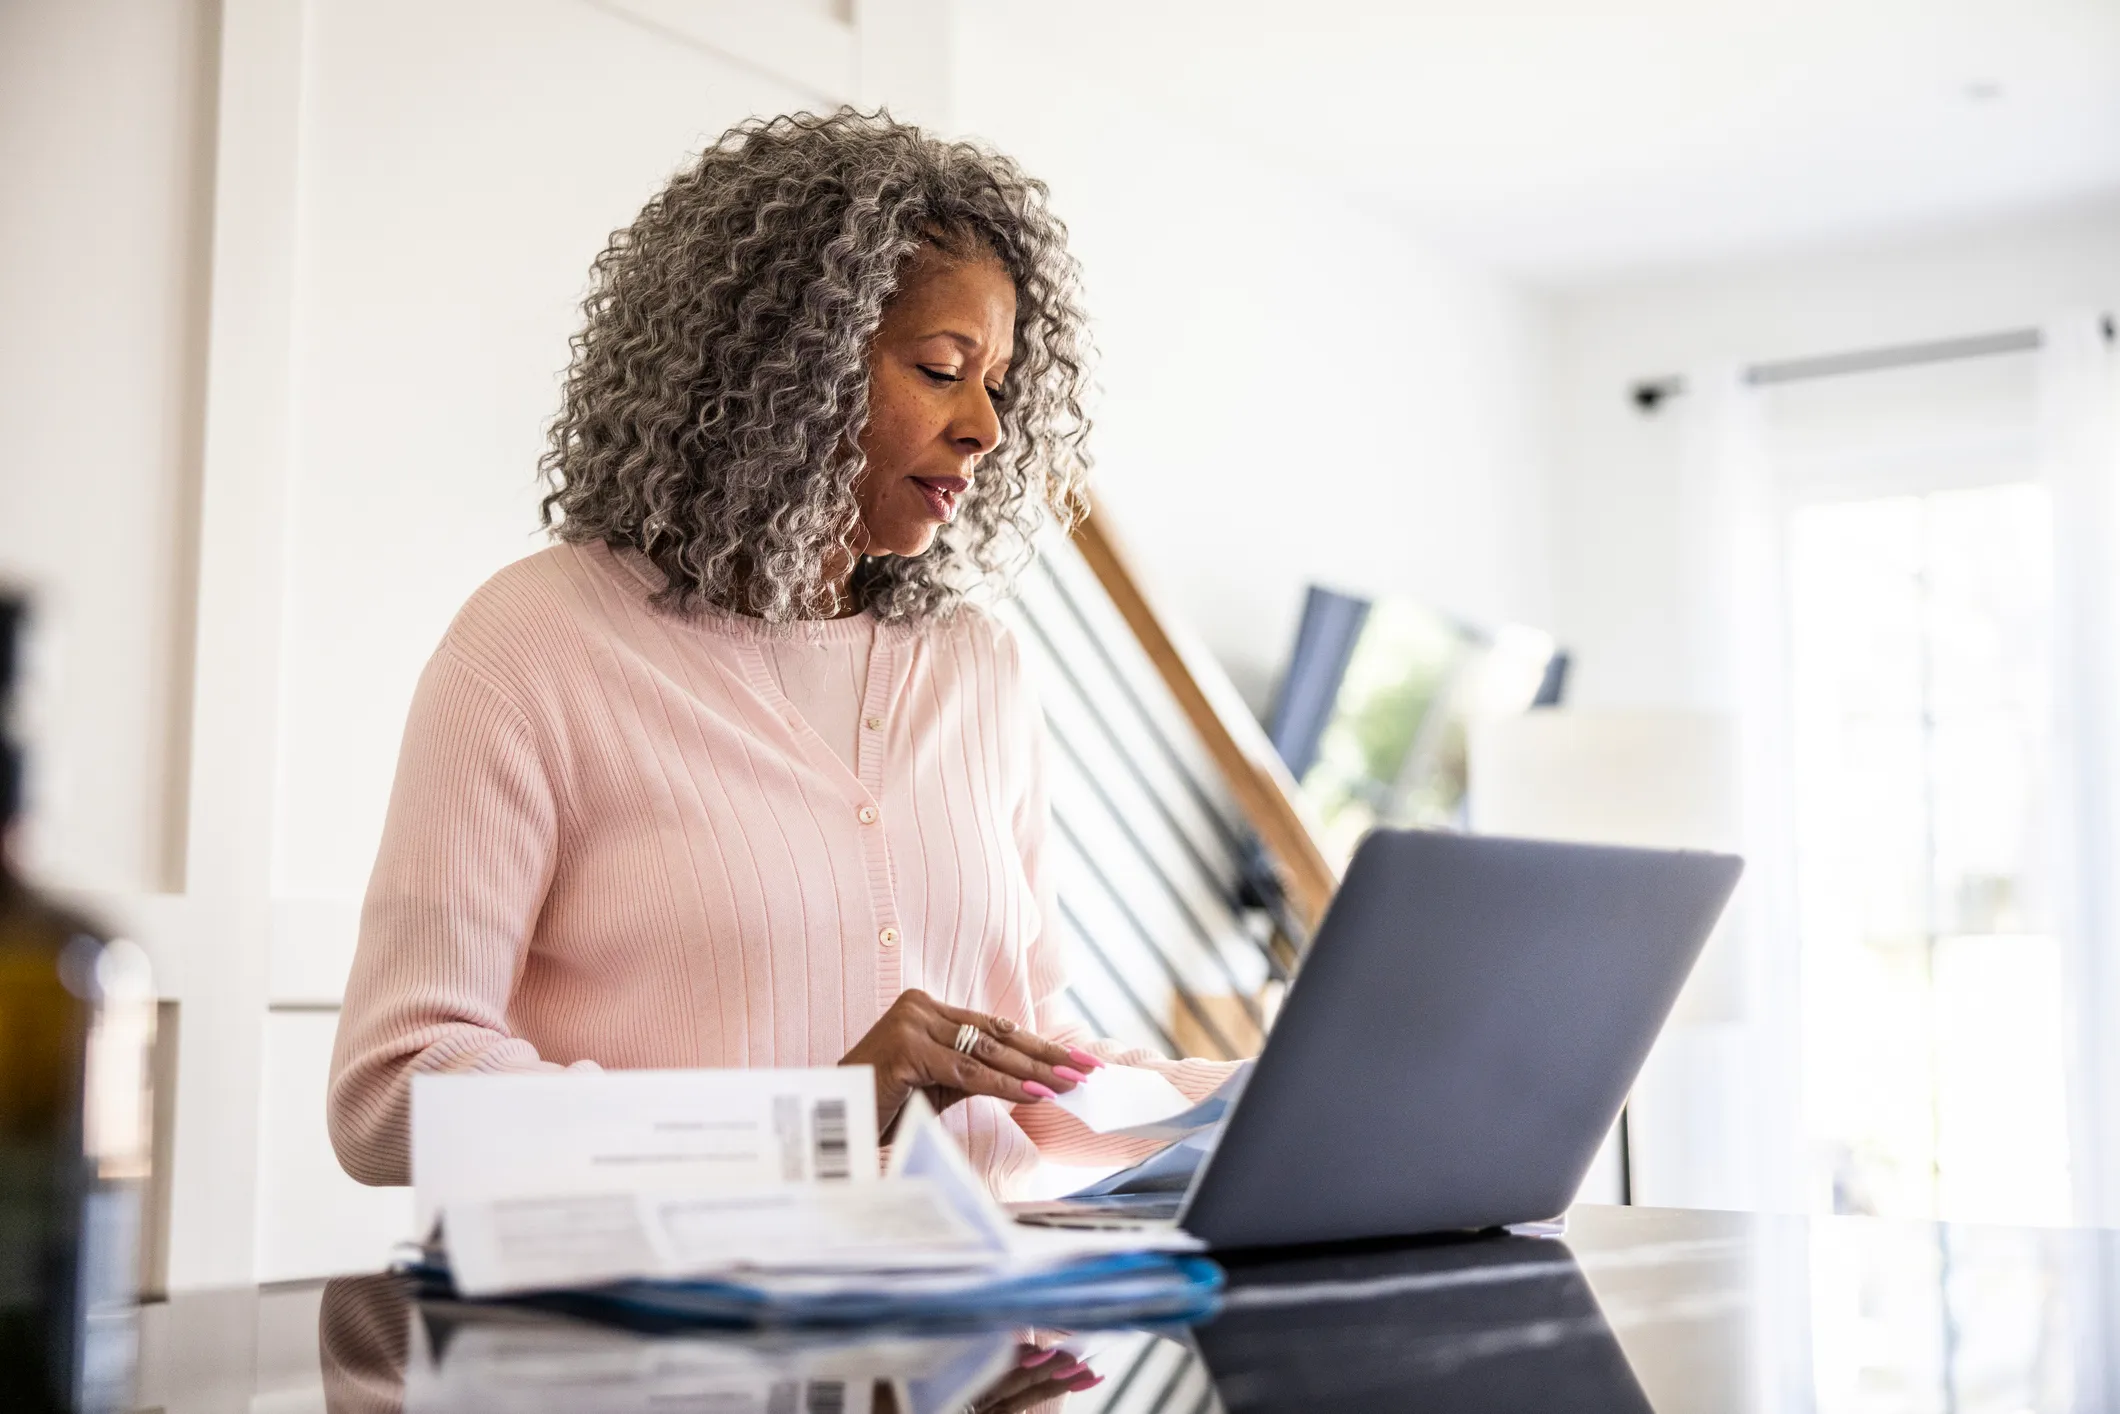
Rolling an old 401(k) into an individual retirement account right after leaving your job sounds like a smart move to simplify your finances. But while some rollovers make sense, it’s important to consider all your options to avoid tax headaches, lost benefits and higher fees.

Here are three questions to ask yourself before you make the switch.

1. What am I giving up by leaving the old 401(k)?

Keeping your money in the 401(k) account of a previous employer isn’t necessarily a bad idea. If your old plan has low fees and strong investment options, it may be beneficial to keep the account intact instead of rolling it over to an IRA or your new employer’s retirement savings account.

The age 55 rule also plays a role. It states that someone can withdraw money from a 401(k) plan penalty-free at 55 if they left their job in or after the year they turned 55. In that case, you can withdraw from a traditional 401(k) while enjoying lower tax rates if you don’t have a salary. This option is not available for IRAs, and you must wait until you turn 59 ½ to avoid penalty fees.

Make sure you understand the pros and cons before you commit to a 401(k) rollover. Just because you left your employer doesn’t mean you should rush to move funds from a 401(k) to an IRA or another account.

2. Will I pay higher fees?

A rollover may be the easy path to simplifying your finances, but some rollovers are costly. Fees can vary, and for 401(k)s, you should consider the investment options.

A 401(k) rollover can make sense, especially if your old plan has excessive fees. In that case, you can save a lot of money with a rollover, but you must compare several IRAs before committing to the right one, or thoroughly research the pros and cons of a new employer’s 401(k) or similar plan.

3. How will this impact taxes?

You can avoid some complicated tax-related questions by doing a direct rollover. This type of rollover involves money moving directly from the 401(k) plan to your new plan.

There’s often more to consider with an indirect roll over. If the check is made payable to the worker, the IRS has a 60-day deadline for that worker to move those funds into another retirement account. If you do not make the deadline, the IRS treats the traditional 401(k) funds as ordinary income and applies a penalty fee if you are under 59 ½, unless an exception applies.

You can still end up with higher taxes if you roll over a traditional 401(k) plan to a Roth IRA. The conversion is treated as ordinary income for tax purposes, but qualified Roth IRA withdrawals can be taken tax-free.

401k Questions Roll
Share. Facebook Twitter Pinterest LinkedIn Email
Previous ArticleMost Savers Lack Clear Plan for Retirement Spending, per Corebridge
Next Article This Underrated Destination on Costa Rica’s South Pacific Coast is Only Accessible By Boat—and Is Surrounded By National Parks
yourlifeafterretirement
  • Website

Related Posts

Finance

Why the 4% Rule Could Fail for Retirement Income

September 13, 2026
Finance

8 Best Online Trading Platforms of 2026

September 13, 2026
Finance

From Buffett to Beyoncé: What Celebrities Have Said About Inheritance

September 13, 2026
Add A Comment
Leave A Reply Cancel Reply

Top Posts

Lizzo’s Cherry Red Manicure Screams “Bad B*tch”

June 5, 20260 Views

Ryan Rozicki Reveals His Knockout Strategy Ahead of Chris Billam-Smith Clash at Zuffa Boxing 7

June 6, 20260 Views

Team Daly/Allen makes birdie on No. 14 at American Family Insurance Championship

June 6, 20260 Views

It’s A Great Time To Buy TIPS For Your Retirement Portfolio

June 6, 20260 Views
Most Popular

How to Watch ‘I Kissed a Girl’ Season 2 in the U.S.

July 1, 202614 Views

No One Likes Medicare Advantage

June 4, 202612 Views
Trending

Alyssa McElheny’s HYROX Tips for Athletes with a Running Background

June 4, 2026

The Muscle-Building Starter Pack: Train Hard, Eat Enough, Recover Right

June 4, 2026
Latest post

Not glamorous, but common: how to manage dandruff at home and when to get help | Well actually

September 13, 2026

7-Day Menu and Comprehensive Food List

September 13, 2026
Facebook X (Twitter) Instagram YouTube LinkedIn
  • About Us
  • Contact Us
  • Privacy Policy
  • Terms and Conditions
yourlifeafterretirement All Rights Reserved 2026

Type above and press Enter to search. Press Esc to cancel.